Beyond Digital Payments - How South African SMEs Can Unlock Funding for New Business
While the rapid adoption of digital and mobile payment systems is helping small and medium-sized enterprises (SMEs) across Africa build verifiable financial records, payment history alone is not enough to secure the funding needed to scale up operations.
This insight comes ahead of the Africa Tech Festival in Cape Town, where the role of mobile money and fintech in supporting SMEs will take centre stage. According to the GSMA’s 2026 report, mobile-money merchant payments reached $155 billion globally in 2025, marking a 42% year-on-year increase, with East Africa accounting for nearly three-quarters of that growth.
Research published by the World Bank indicates that businesses accepting electronic payments are roughly three percentage points less likely to be fully credit-constrained, an effect particularly pronounced among smaller, younger firms lacking audited financial statements.
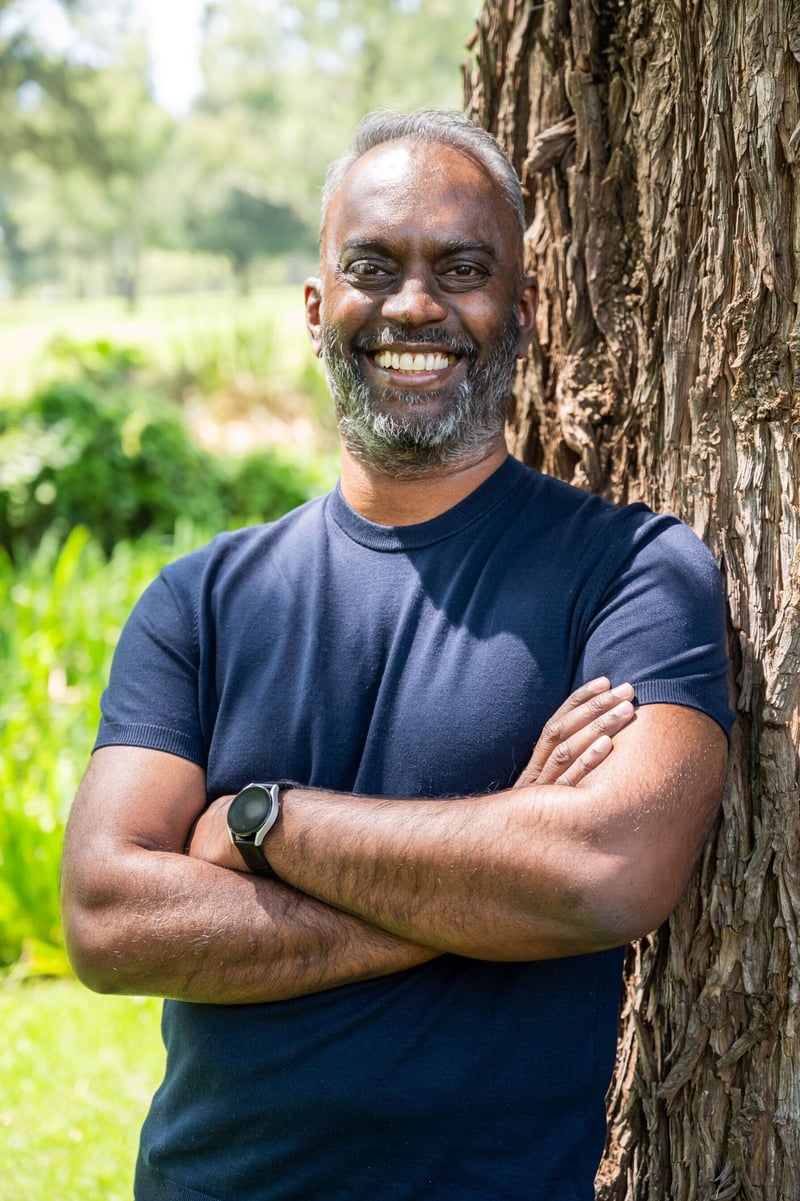
However, Andrew Maren, Founder and CEO of fintech firm ProfitShare Partners, emphasizes that whilst digital payment records bridge an important information gap for lenders, they only solve part of the growth equation.
"A digital payment history demonstrates that a business has active customers, which is a vital starting point," says Maren. "However, it does not explain how a business will handle its next major commercial opportunity. Consider a distributor with modest, steady sales that suddenly lands a large corporate purchase order. Their historical payment records show they trade, but they do not prove whether the SME can execute the contract profitably or whether the corporate buyer is creditworthy."
Maren argues that the next phase of African fintech development requires closer cooperation between payment providers and funding institutions to assess the true commercial potential of specific transactions rather than relying solely on past performance.
ProfitShare Partners addresses this gap by structuring short-term capital directly around verified purchase orders, contracts, and invoices. By evaluating the buyer’s credibility and the underlying economics of the specific deal, this model enables SMEs to fulfil large orders without requiring traditional collateral or lengthy financial track records.
As payment ecosystems continue to evolve across the continent, Maren advocates for responsible information sharing, robust data safeguards, and financing models aligned with how small businesses actually operate.
"Getting paid digitally proves an SME has traction," Maren concludes. "The real test for the financial sector now is ensuring these businesses receive the capital required to deliver the work they have secured, allowing them to build an even stronger trading history."
Release information
Issued on behalf of
Profit Share Partners
Media contact
Wonder Communications SA
Fazielah Williams