The Capital Reset - Sustainability, Competitiveness and Investment Readiness is a Two-Sided Affair
Answering investor and lender ESG questions is now part and parcel of due diligence and ongoing performance monitoring when raising capital. But investment readiness is a two-sided affair. While African businesses must demonstrate that they have identified and are managing their material ESG risks, they must also have the harder, more valuable skill of knowing which questions matter and the confidence to challenge what is not relevant or does not fit. Capital providers, regulators, and the standard-setters behind these requirements must, in turn, understand the African business context and learn from what works here. Finance leaders have a critical role to play in redefining this relationship,
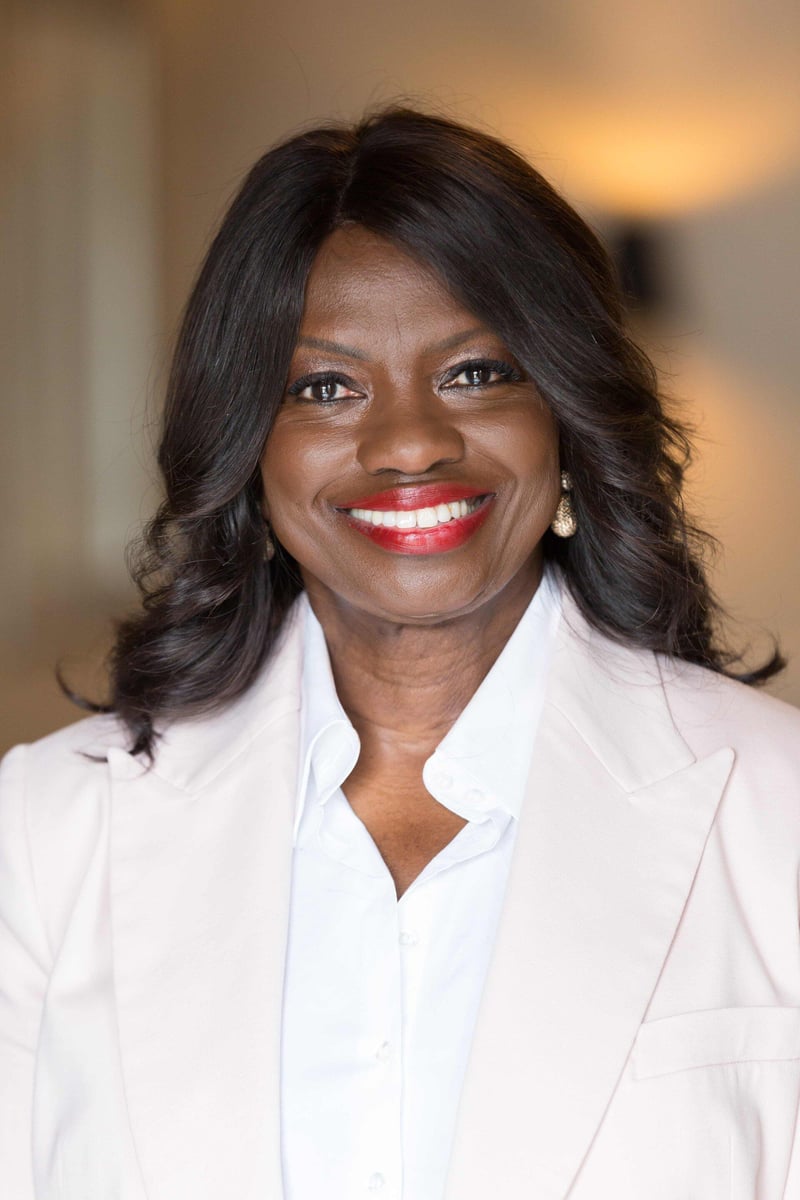
Opinion by Rosalind Kainyah MBE, International Speaker on ESG and Responsible Business. Delivered at the ENGAGE Africa 2026 Conference, hosted by AICPA and CIMA in Cape Town.
When ESG comes up in conversations about investment readiness in Africa, the focus usually falls on compliance. Can the business meet the standard, answer the investor’s questions and back up its answers with evidence? Those answers shape how investors assess risk, and risk sets the cost of capital.
Some African businesses can fall short here. That is seldom because they are poorly run businesses. More often, they simply aren’t able to show investors what they need to see. Informal record-keeping, governance structures that lean heavily on a founder or dominant CEO, and an inability to show how key ESG risks are managed all raise perceived risk, and the cost of capital rises accordingly. Context may explain these gaps, but only closes them with the evidence to prove.
But investment readiness is not simply about getting better at answering someone else’s ESG scorecard. African businesses have more agency in this relationship than we often recognise.
Too often, partnership is treated as a one-way transfer of standards and requirements. We are told what to do and rarely asked what we can contribute. Yet many African SMEs already “do” sustainability out of necessity, not as a performance metric. They run circular models because linear consumption is unaffordable. They invest in community trust because the community is both their labour pool and their customer base. It is also their social licence to operate, which can matter as much as any legal licence. These businesses know how to innovate under constraint, and they understand that sustainability which doesn’t create or protect value will never last.
None of this means investors are wrong to ask questions or require compliance with certain standards. ESG factors affect risk, growth, cash flow, market access, operating costs and the quality of management, so capital providers rightly assess businesses against those factors. But capital is not a gift. Yes, an African business needs an investor's capital. But there is another side of the ledger: that business may be giving the investor a growth opportunity to multiply their dollar. Currency liquidity and exit risks are real and belong in the price, but so does the upside.
That is the basis for a two-way conversation between parties who each bring something valuable to the table.
The Capital Reset should be a bridge that people are willing to cross in both directions.
Standards are useful. Blind application is not.
#1: Investment readiness is not ESG readiness
#2: Ask what sits behind the question
#3: “Made over there” may not fit over here
#4: Five questions for an investment-ready business
From rule-taker to participant
There is nothing wrong with global standards. They give everyone a common measuring line.
But a global standard can be useful without every local application of it being appropriate or even relevant. The starting question for African businesses is simple. What is this provider of capital trying to understand about our business, and how does that connect to our commercial drivers? The Chief Financial Officer is central to that answer.
There are four fundamentals that African businesses and investors need to unpack and understand in this Capital Reset.
An excellent sustainability report, aligned to the best global standards, does not make a company investable. It still has to be a good business.
The sustainability conversation is sometimes strangely siloed from the fundamentals of running a business. Every piece of information an investor requests serves one purpose: to judge the sustainability and robustness of a business and whether the business can deliver the expected return. ESG performance feeds into that judgement. A strong business that cannot explain its ESG impacts, and how it manages them, will be hard for an international investor to assess. Its strengths may be real, but nobody can see them.
Investment readiness means knowing which ESG issues affect your performance and value, managing them well and being able to prove it. It also means having the confidence to push back on issues that don’t apply. The CFO or finance leader should be able to translate sustainability issues into financial and strategic terms, decide what information will genuinely help investors and challenge assumptions where necessary. The real task of interpreting the gap between operational reality and what capital expects.
Investors often arrive with a set list of questions. Many businesses believe they must answer every one or lose the opportunity. A better first step is to ask why the investor needs the information.
This may sound radical when many African businesses struggle to access capital at all. But I sit on the boards of international companies that also need finance, and there the conversation with investors is far more commercial. Both sides interrogate ESG assumptions and requirements. African businesses should have the confidence, backed by evidence, to do the same.
One, a London-listed company that I sit on the board of received an investor questionnaire with more than 900 ESG-related questions. Only 15 applied to our business. We answered those 15 and explained why the rest were not relevant. In that case, the investor continued to invest. That is judgement.
Even when a question does apply, it pays to understand its purpose. A question on water usage may really be about whether production depends on water availability. Labour questions may be about whether strikes, injuries or workforce instability could interrupt operations. Climate questions probe exposure to physical or transition risk. Governance questions ask whether the people in control can be trusted with someone else’s money.
A second question is “Which of our commercial drivers does this E, S or G issue touch?” For example, “Does it have implications for our growth and market access, our operational continuity, operating costs, management quality or reputation?” If none, you can say: “This does not apply to our value model and here is why?”
Understanding the reason and the link to creating or protecting value for your business tells you what evidence is needed. This is where the finance leader adds real value, shifting the conversation from “What ESG information must we provide?” to “What is this investor trying to understand about our ability to perform responsibly and successfully?” The best businesses have worked this out before they are asked.
By “made over there”, I refer to standards and frameworks designed elsewhere and assumed to travel unchanged. Rules made in Brussels, for example, do not change at Europe’s border. They travel across and through lender, investors and supply chains to businesses everywhere, including here on the continent.
A European business discussing the energy transition may assume a reliable electricity supply, while theAfrican manufacturer is focused on whether the lights will come on tomorrow. A supply chain traceability requirement may assume suppliers can produce the digital data. That assumption breaks down quickly for an agribusiness buying from hundreds of smallholder farmers.
These differences don’t make the underlying environmental or social issue irrelevant, and context is never an excuse for poor performance. But context does shape the nature and scale of a risk, and how best to manage it. The African business needs to understand the outcome the investor wants. It must then explain what will work locally and how that still delivers the outcome. There is a difference between excusing and adapting. Excusing says “our conditions are different, so we cannot meet your standards”. Adapting says “Our conditions are different. We understand why you are requiring this of us, but we cannot meet it in the way you suggest. Here is how we will and here is the evidence.”
An investment-ready African business should be able to answer five questions convincingly:
1. What environmental, social or governance factor drives and threatens the value of this business?
2. Which specific ESG issues actually matter to those value drivers?
3. How are we actively managing those issues?
4. What evidence can we produce to show we are managing them effectively?
5. Where an investor requirement does not fit our circumstances, can we explain why and propose a credible alternative?
That fifth question is rarely asked, and so rarely answered. It is a finance leadership question, not merely an ESG one, and it needs solid evidence behind it. Without that evidence, a proposed alternative sounds like an excuse.
The conventional view of the Capital Reset is that investors expect more and African companies must catch up. We need to see it differently.
African businesses must understand international requirements to access international capital. Understanding the rules, though, does not mean surrendering the right to question how they are applied. Companies should negotiate intelligently with investors rather than accept every request by default.
Professional and industry bodies can produce credible African data, so investors are not pricing African risk on assumptions, and help shape the standards used to assess them. African capital markets need to mobilise more African capital so that external investors are not the only ones setting the terms.
The more Africa builds its own institutional capital, data and expertise, the more it can influence what “investability” means. That does not mean abandoning ESG standards. It means room to apply them in ways that reflect real, lived conditions while still driving improvement.
Sometimes that will mean complying with investor requirements. Sometimes it will mean adapting them while still delivering the results. And there will be moments when we need to say: “This way doesn’t work here. We understand the outcome you need. We have a better way to deliver it. Let us show you.”
The quiet but persistent assumption that more African input would produce “easier” standards is patronising. Contextual relevance does not cancel out rigour.
African businesses should not behave as if they need to be rescued, discovered or taught how to run. Many are thriving under conditions that would test the most sophisticated companies anywhere. Investors, in turn, need the curiosity and humility to listen more carefully to markets they have often overlooked and underestimated.
Africa does not need to reject global capital or global standards. Nor should it assume that good practice can only travel in one direction.
This is not the responsibility of just the “sustainability person”. It also belongs to the person investors look to first for assurance about the quality, performance and value of the business.
Finance leaders have the skills and knowledge to take the lead here. They must.
About the author
Rosalind Kainyah MBE is an international speaker and advisor on sustainability, ESG, and responsible business, with over 30 years’ experience in legal, executive, and board roles. She sits as a Non-Executive Director on the boards of listed and private companies in the UK and Africa, chairing Sustainability and Remuneration Committees. Rosalind founded Kina Advisory in 2013, providing advice on ESG strategy to companies operating in Africa. Her earlier roles included senior executive positions at Tullow Oil plc and De Beers, and as an environmental and corporate lawyer at Linklaters. She designs and delivers ESG Masterclasses for boards and senior executives and co-authored Simplifying Sustainability: A Handbook for African SME Leaders. She is Vice Chair of African Gifted Foundation UK.
Release information
Issued on behalf of
AICPA & CIMA
Media contact
Teresa Settas Communications
Teresa Settas